
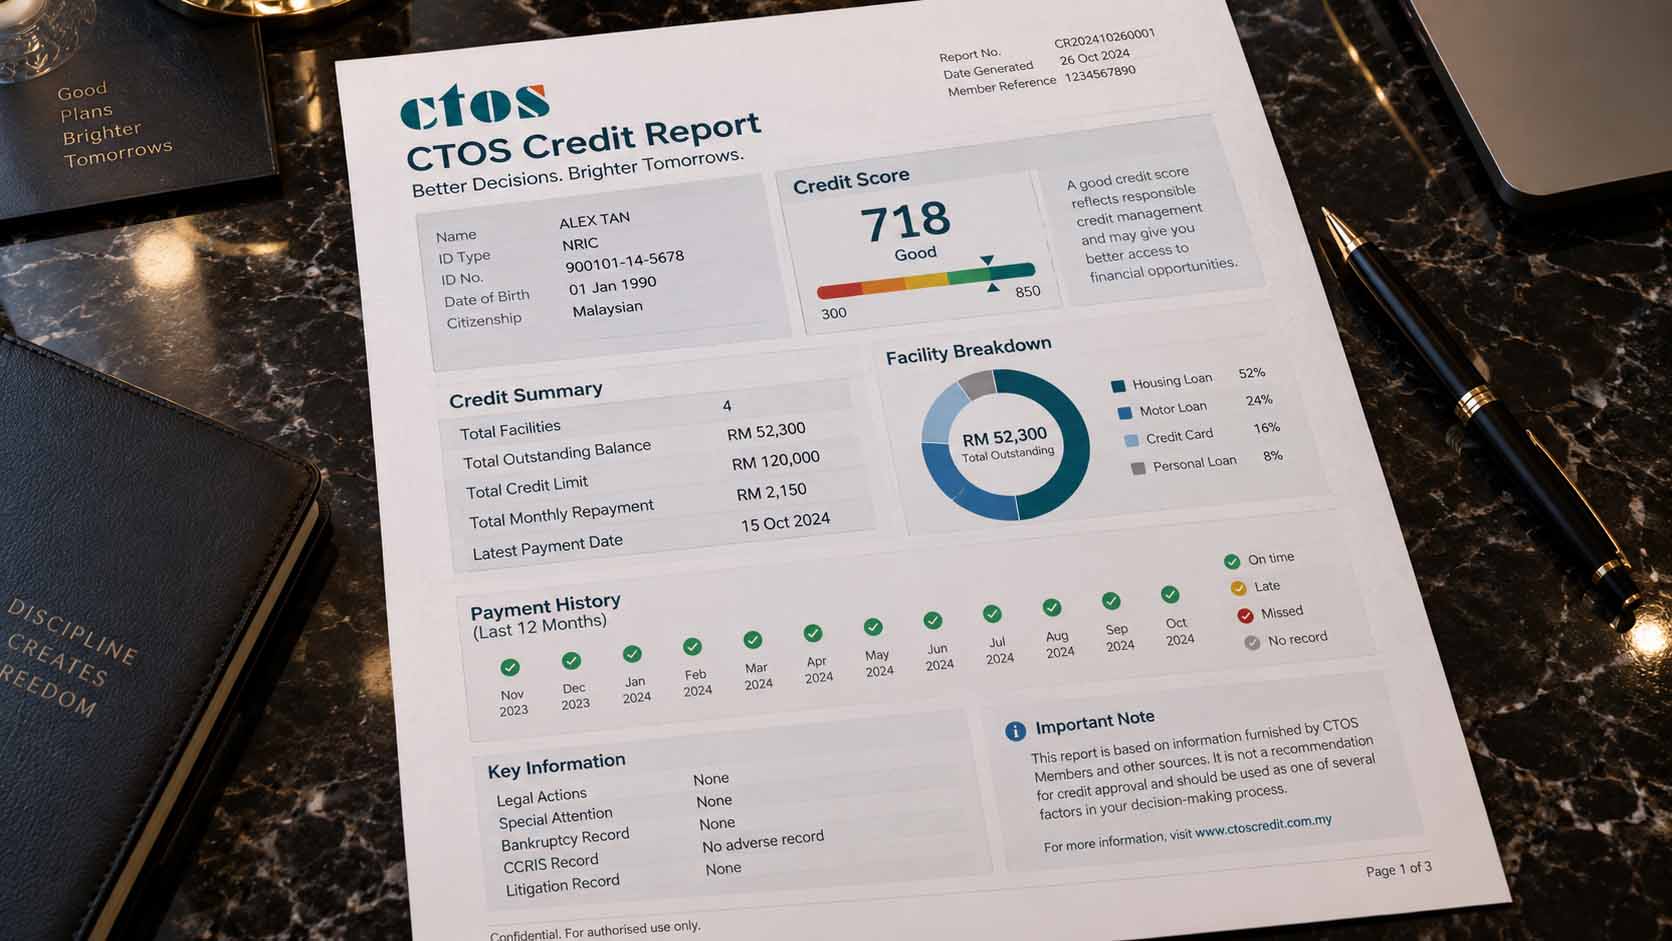
CTOS launched its revamped mobile app in September 2026 with score comparison, month-by-month tracking, digital credit reports, business reports, identity monitoring and credit-product comparison tools. The update makes credit information easier to explore—but a CTOS Score is still only one part of a lender’s assessment.
The short answer: A CTOS Score is a three-digit indicator of credit risk. A CTOS credit report can include the information behind that score, including CCRIS records. A Malaysian bank does not approve a home loan from one number alone: it also assesses affordability, the applicant’s documents and its own lending policy.
Alrizq Assets Sdn. Bhd. is an appointed CTOS agent. Through our CTOS & Land Search Request service, you can request the report suited to your needs and get help understanding the information before you submit a financing application.
Request Your CTOS Report Through Alrizq
CTOS Score, CTOS report and CCRIS are not the same thing
These terms are often used interchangeably, but they describe different things.
| Item | What it is | What it can tell you |
|---|---|---|
| CTOS Score | What it isA three-digit credit-risk indicator generated by CTOS, currently ranging from 300 to 850 | What it can tell youA quick view of relative credit risk; a higher score generally indicates lower risk |
| MyCTOS Basic Report | What it isA CTOS consumer report without CCRIS records or a CTOS Score | What it can tell youIdentity information, business interests, litigation or bankruptcy information, and trade references listed by CTOS |
| MyCTOS Score Report | What it isCTOS’s consumer full-report product | What it can tell youThe Basic Report information, CTOS Score and CCRIS records in one report |
| CCRIS Report | What it isA factual credit report operated by Bank Negara Malaysia | What it can tell youFinancing, repayment conduct and application information reported by participating institutions, generally covering the most recent 12 months |
| Bank Assessment | What it isThe lender’s own decision process | What it can tell youHow the lender evaluates credit information, affordability, supporting documents and its internal policy |
Bank Negara Malaysia does not assign a CCRIS score or maintain a borrower “blacklist”. It provides factual credit information. Each financial institution makes its own decision and can interpret the same information differently. CTOS separately explains the inclusions in its consumer credit report and score products.
What is new in the CTOS Digital app?
CTOS says the updated app includes:
- score comparison with people in the same age group or nationality;
- month-by-month CTOS Score tracking;
- access to digital reports containing CCRIS information, repayment history, active facilities, balances and legal records;
- CTOS SecureID alerts for identity and credit-profile changes;
- business credit reports; and
- CreditFinder comparisons for selected loans and credit cards.
Some reports and monitoring features are paid. If your goal is to prepare for a financing application rather than simply monitor your score, Alrizq can help you choose and request the appropriate CTOS report. Products, features and prices can change, so rely on the current inclusions displayed on our request page.
What does a CTOS Score show?
The score condenses selected credit information into one risk indicator. CTOS says the score considers payment history, amounts owed, length of credit history, credit mix and new credit.
That number is useful, but it does not tell you a particular bank’s approval threshold. It also does not replace the account-level information in a credit report or the lender’s affordability assessment.
Two applicants with the same score can still have different balances, repayment patterns, recent applications and financial circumstances. A bank may therefore reach different decisions even when their headline scores are similar.
What may a Malaysian bank check before approving a home loan?
A lender may assess several inputs together.
1. CCRIS information
Bank Negara Malaysia’s CCRIS guidance explains that the report can show credit applications and account details reported by participating institutions, including facility type, credit limit, outstanding balance, instalment and repayment conduct.
CCRIS does not necessarily contain every debt. Bank Negara Malaysia states that it covers specified information from participating institutions, not every credit provider.
2. Information from a credit reporting agency
A bank may also use information from a registered credit reporting agency such as CTOS, Credit Bureau Malaysia or Experian, as explained in Bank Negara Malaysia’s CCRIS FAQ. The provider and report used can vary between lenders and applications.
This means the report you buy for self-review is not necessarily the exact screen, scorecard or product used inside a bank.
3. Affordability
Under Bank Negara Malaysia’s responsible-financing requirements, banks assess whether the applicant can afford the proposed repayment after considering income and existing obligations. Debt service ratio, or DSR, can be one input in that assessment. Current affordability assessments may also consider whether sufficient income remains for essential living expenses.
A good CTOS Score does not by itself prove that the requested loan is affordable.
4. Application details and documents
The bank also considers the information and supporting documents supplied with the application. Missing, inconsistent or insufficient evidence can affect the outcome independently of the CTOS Score.
5. The bank’s own lending policy
Banks have different policies and risk appetites. A decline from one bank does not automatically mean every bank will make the same decision, and no public score guarantees approval.
What about BNPL and digital financing?
Do not assume that every buy-now-pay-later account appears in CCRIS. The system contains information from participating institutions, and reporting can differ by provider and product.
Malaysia’s Consumer Credit Act 2025 licensing framework began bringing BNPL providers under formal regulation in 2026. That regulatory change does not, by itself, mean every BNPL balance is universally visible in every CCRIS or CTOS report. Applicants should still disclose commitments accurately when a lender asks for them.
When is a score check enough?
If you only want a quick indication of your credit standing, the CTOS Score can be a useful starting point.
If you plan to apply for a home loan, refinancing or another major facility, review the underlying report as well. This can help you:
- check whether account and repayment information is accurate;
- identify unfamiliar applications or records;
- see recent CCRIS conduct and outstanding commitments;
- raise a correction request where information appears wrong; and
- discuss affordability and documentation with your lender or adviser before applying.
For a guided CTOS report request, use Alrizq’s service before applying. We can help you select the relevant report and understand what the reported information means for your preparation. The report remains an information and preparation tool; it is not a bank approval.
Why can a good score still lead to a declined application?
A score measures credit risk; it is not an approval certificate. An applicant can have a good score but still fall outside a lender’s affordability calculation, provide insufficient supporting documents or fail a bank-specific policy requirement.
The reverse is also important: a lower score does not mean Bank Negara Malaysia has “blacklisted” the applicant. CCRIS does not maintain a blacklist, and different lenders can assess the same facts differently.
Get your CTOS report through an appointed CTOS agent
Alrizq Assets Sdn. Bhd. is an appointed CTOS agent. Our CTOS & Land Search Request service provides a direct assisted route to request an available CTOS report before a home-loan, refinancing or other financing application.
Using Alrizq can help you:
- choose between the available individual and SME report options;
- complete the required request and consent process;
- understand the main sections and information shown in the report;
- identify information that may need clarification or correction; and
- discuss the report alongside your DSR, documents and financing plan.
We do not replace the bank’s assessment and cannot guarantee approval. Our role is to help you prepare with clearer information before an application is submitted.
See the current report options, inclusions and prices on the request page. The appropriate product depends on whether you need a basic search, CCRIS information, an individual score or an SME score.
For real estate agents and negotiators
A buyer who knows only a headline CTOS Score may still have unanswered questions about affordability, account-level information or documents. Encouraging buyers to review their information early may reduce avoidable surprises later in the transaction.
Agents should not promise approval or interpret a score as a bank decision. The useful role is to encourage accurate information, early preparation and referral to the appropriate lender or qualified adviser.
Frequently asked questions
Is a CTOS Score the same as a CTOS credit report?
No. The CTOS Score is a three-digit risk indicator. A CTOS credit report is the document containing credit information. CTOS’s consumer MyCTOS Score Report includes the Basic Report information, the score and CCRIS records.
Is CTOS the same as CCRIS?
No. CCRIS is operated by Bank Negara Malaysia. CTOS is a registered private credit reporting agency. A CTOS report may include CCRIS information when the applicable product and consent requirements are met.
Does checking my own CTOS report affect my score?
CTOS says no. A self-check is a personal inquiry and does not affect the CTOS Score. A lender inquiry following a credit application is different and can be visible to lenders.
Does every bank use the CTOS Score?
Not necessarily. Banks use CCRIS and may obtain information from CTOS or another registered credit reporting agency. Each bank also applies its own affordability and credit policies.
Does a good CTOS Score guarantee a home-loan approval?
No. A bank also assesses affordability, application information, supporting documents and its own lending criteria.
Can I request a CTOS report through Alrizq?
Yes. Alrizq Assets Sdn. Bhd. is an appointed CTOS agent. Use our CTOS & Land Search Request service to view the available report options, current inclusions and prices and to submit your request.
Is an eCCRIS report the same as a CTOS report?
No. Bank Negara Malaysia’s eCCRIS service provides your CCRIS information. A CTOS report may combine CCRIS with a CTOS Score and other credit information, depending on the product selected. Alrizq can help you request the appropriate CTOS report for your needs.
Should I review my report before applying for a home loan?
It is sensible to review it early enough to check the information and address possible errors. A report is a preparation tool, not an approval guarantee.